


What happens if an uninsured or underinsured driver hits your motorcycle in New York?
Getting injured in a motorcycle accident in NYC can be absolutely financially devastating, particularly if the driver who caused the accident has no insurance at all or is only carrying the minimum liability coverage that is required by New York law. The motorcyclist may end up with serious injuries requiring emergency surgery, hospitalization, a long period of physical therapy, and months out of work, only to find that the negligent driver has either no insurance or very minimal insurance. This is particularly difficult because motorcyclists are generally excluded from New York’s No-Fault system and don’t have the automatic medical and wage loss benefits available to many car accident victims.
A driver who is uninsured or underinsured doesn’t necessarily mean that an injured motorcyclist is going to be left with nothing. Depending on the circumstances, the motorcyclist may be able to claim under uninsured motorist coverage, supplementary uninsured/underinsured motorist coverage, the insurance of another at-fault party, or indeed through a personal injury action. All of those claims are subject to a host of policy provisions, strict notice requirements, coverage disputes, and the rigors of the legal process, so it’s not always possible to recover. Understanding the difference between uninsured and underinsured motorist coverage is vital to protecting your financial future.
At Greenstein & Pittari, LLP, we are New York City motorcycle accident lawyers, and we represent injured riders across NYC (Manhattan, Brooklyn, Queens, the Bronx, Staten Island, Long Island, and Westchester County). We investigate accidents, identify available insurance, and pursue compensation when the driver was negligent and uninsured or underinsured. If an uninsured driver has injured you, an underinsured driver, or a hit-and-run driver, please call Greenstein & Pittari, LLP at 1-800-VICTIM2 (1-800-842-8462) for a free consultation. Don’t Be a Victim Twice.
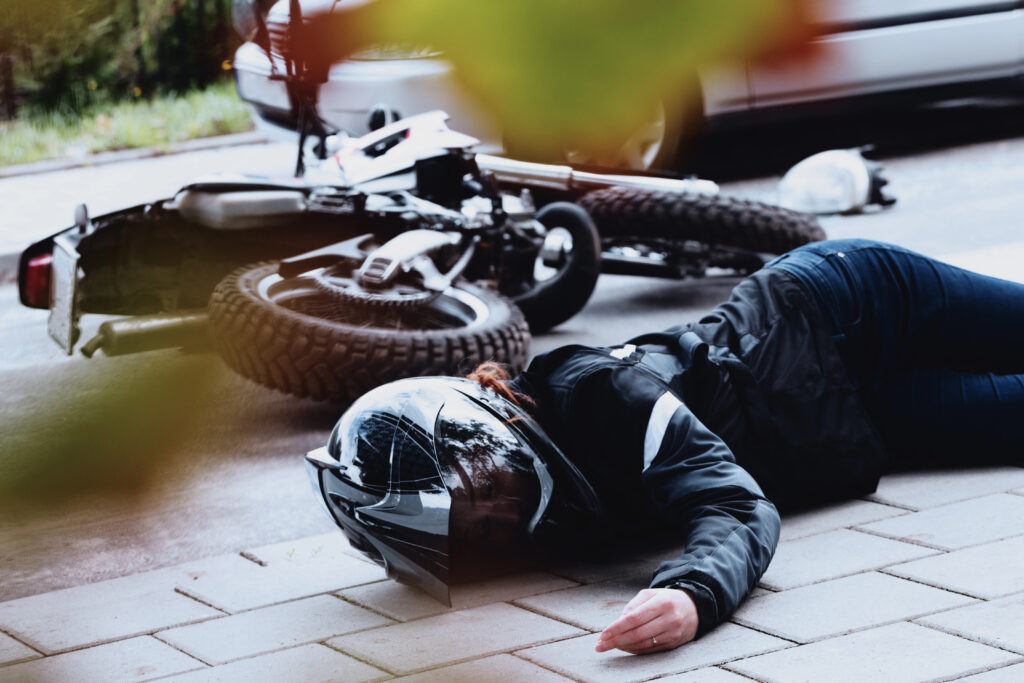
What happens if an uninsured driver causes a motorcycle accident in NYC?
If an uninsured driver is involved in a motorcycle accident in NYC, the injured motorcyclist may be able to recover compensation via their own uninsured motorist coverage or through a personal injury claim against the at-fault driver. New York requires all motor vehicle owners to carry liability insurance, but many drivers operate without it. Some don’t have insurance, others have allowed their policies to lapse, and some operate a vehicle that was never insured in the first place. When an uninsured driver causes serious injury, the victim is left with potentially huge medical bills and lost income and no liability insurance policy to fall back on. Uninsured motorist coverage protects in certain circumstances when the at-fault driver does not carry the required bodily injury liability insurance. Benefit availability depends on the insurance policy, the injured person’s status, the vehicles involved, and compliance with the policy terms. An attorney should immediately look into the other driver’s insurance and identify all possible sources of compensation.
What is uninsured motorist coverage for motorcycles in New York?
Uninsured motorist coverage (commonly known as UM coverage) is insurance that will pay for bodily injury to an eligible insured person resulting from the actions of a legally responsible driver who has no applicable liability insurance. New York generally requires uninsured motorist bodily injury protection as part of a qualifying motor vehicle liability policy (including a motorcycle policy). The coverage is subject to statutory requirements, policy definitions, exclusions, and conditions. It differs from ordinary liability insurance, which protects the insured driver against claims made by injured third parties. A motorcyclist injured by an uninsured automobile driver may have a claim under the rider’s own motorcycle policy. The existence of coverage does not, of course, mean the rider is entitled to payment. The rider would generally have to prove the uninsured driver was legally responsible, the nature of the injuries, and compliance with the relevant insurance requirements.
What’s the difference between uninsured and underinsured motorist coverage?
Uninsured motorist coverage is available where the at-fault driver has no qualifying liability insurance or where the vehicle is otherwise classified as an uninsured motor vehicle. Underinsured motorist coverage is available when the at-fault driver has liability insurance, but its limits are inadequate relative to the injured person’s applicable supplementary coverage. In New York, this supplementary coverage is generally provided via Supplementary Uninsured/Underinsured Motorists (SUM) coverage. For instance, a driver may have $25,000 in bodily injury liability coverage, and the injured motorcyclist may have $250,000 in applicable SUM coverage. If the motorcyclist is seriously injured, SUM coverage could be significant once the at-fault driver’s liability coverage is exhausted. SUM coverage is subject to policy limits, offsets, statutory requirements, and conditions regarding exhaustion and settlement. The stated SUM limit should not be taken as an amount payable in addition to the other driver’s insurance. An attorney will need to review the policies and determine the actual available benefits.
Is uninsured motorist insurance required for motorcycles in New York?
New York generally requires a motorcycle liability policy to contain statutory uninsured motorist bodily injury coverage (subject to applicable insurance requirements). This is a different product from optional, higher-limit supplementary uninsured/underinsured motorist coverage. The minimum required uninsured motorist coverage will generally match New York’s basic bodily injury liability limits (i.e., $25k per person and $50k per accident for bodily injury), plus the applicable statutory provisions for certain death claims. The minimum coverage will generally only provide very limited financial protection in the event of a serious motorcycle collision. A rider who suffers multiple fractures, a TBI, or a permanent disability could easily find themselves in a position where their losses are many times in excess of the minimum coverage. Purchasing higher applicable SUM limits may provide additional protection (depending on the policy and available options). Review your insurance declarations and endorsements to confirm what you actually have, rather than assuming a motorcycle liability policy will automatically provide sufficient coverage in the event of a catastrophic injury.
Is underinsured motorist coverage required for New York motorcyclists?
Higher-limit supplementary uninsured/underinsured motorist coverage is not necessarily required on every motorcycle policy at the limits a rider may actually need after a serious crash. New York’s SUM framework provides additional protection where available under the policy, and whether it is available and required to be offered is a matter of statutory and regulatory requirement. Riders should check their policy declarations to see whether they have purchased SUM coverage and what the limits are. A motorcyclist who relies only on minimum coverage may find the protection available after being hit by a driver with limited liability insurance isn’t enough. This is a real issue as motorcycle accidents are so frequently the result of injuries which will require surgery, rehab, and a significant amount of time off work. An attorney reviewing an underinsured motorist claim should obtain the full insurance policy (including all endorsements) rather than relying only on the coverage amounts shown on an ID card.
How much uninsured motorist coverage should a motorcycle rider have in NYC?
Motorcyclists should review their uninsured/underinsured motorist (UIM) coverage limits and consider whether they’re sufficient to cover the potential financial consequences of a serious collision. A single motorcycle accident can result in a very long hospital stay, multiple operations, permanent disability, and a significant loss of income. The at-fault driver’s liability coverage may not be enough to cover those losses. UIM coverage, where available, can be an additional source of compensation (subject to the policy terms and applicable law). The right amount of coverage will vary from rider to rider based on their financial situation, the insurance they already have, the coverage options available to them, and the cost of the additional protection. $100k, $250k, or higher may be appropriate in some cases, but there is no one-size-fits-all answer. Greenstein & Pittari, LLP recommends that motorcyclists take time to review their policies before an accident to ensure they understand the level of protection they actually have.
Can you recover compensation if the at-fault driver has only $25k in insurance?
Yes. An injured motorcyclist could potentially go beyond the negligent driver’s $25k bodily injury liability limit and claim additional damages if another applicable insurance policy or liable party exists. New York’s minimum bodily injury liability limits are often insufficient in the event of a motorcycle collision that results in serious orthopedic injuries, spinal injuries, or traumatic brain injury. A motorcyclist with applicable higher-limit SUM coverage may have a claim for additional covered damages (subject to policy limits, offsets, and conditions, of course). Other sources of recovery could be commercial auto insurance, employer’s liability, excess policies and claims against other negligent parties. The negligent driver may also be personally liable for damages in excess of the insurance available. However, in practice it can be very difficult to collect an uninsured judgment. Before accepting a policy-limit settlement, an attorney must determine whether the driver was working at the time of the accident, whether the vehicle was commercially insured, and whether any other policies apply.
How does SUM coverage work after a motorcycle accident?
Supplementary Uninsured/Underinsured Motorists (SUM) coverage can provide additional compensation where an insured motorcyclist is legally entitled to damages from a negligent driver whose liability coverage is inadequate under the policy and the applicable laws and regulations. So, for instance, if a motorcyclist has $250k in applicable SUM coverage and is involved in an accident with a negligent driver who has only $25k in bodily injury liability coverage, and the rider is in fact legally entitled to damages in excess of the $25k the negligent driver has, a SUM claim could provide that additional compensation. The amount payable, however, is subject to the SUM endorsement, applicable offsets, the terms of the coverage, and other such factors. In a simple case, the $25k recovered from the negligent driver may reduce the amount available under the SUM coverage, rather than allowing the rider to collect $250k on top of the $25k. The calculation can become considerably more complex when multiple claimants, vehicles, policies, and/or layers of insurance are involved.
Can you collect both the at-fault driver’s insurance and your motorcycle SUM coverage?
An injured motorcyclist may be able to get compensation from the negligent driver’s liability insurance and may also access benefits under applicable SUM coverage. The two sources of compensation are generally not additive to an unlimited extent. The New York SUM endorsements contain specific language regarding limits, offsets, and the relationship between the negligent driver’s liability and the insured person’s own SUM coverage. For instance, a rider with a $250k applicable SUM limit who recovers $25k from the negligent driver’s liability insurer may be able to access additional benefits under the remaining SUM coverage, provided there is proof of damages and the policy terms are met. The rider cannot simply assume that the full $250k of SUM coverage is available in addition to the $25k they have already received from the negligent driver’s insurer. The insurer may well dispute the extent of the injuries and the amount of damages. An attorney should review the full policies and applicable endorsements before determining potential recovery or advising the rider on whether to accept a settlement.
What happens if the at-fault driver’s insurance company denies coverage?
A denial of liability insurance coverage could give rise to an uninsured motorist claim (depending on the reason for the denial and the policy wording). The insurer may argue that the negligent driver’s policy had been canceled before the incident, that the vehicle was not covered at the time of the collision, or that some other exclusion applies. A denial of coverage does not necessarily mean that the vehicle is uninsured for all purposes. The denial may be wrong; it may reflect a dispute over the policy’s interpretation; or it may result from an investigation into other available coverages. The attorney will need to obtain the denial letter, policy information, cancellation records (where appropriate), and any other relevant documentation. It may be necessary to contest the insurer’s position on liability coverage while preserving the injured motorcyclist’s rights under an applicable UM policy. Time is of the essence in this situation, as notice requirements may apply even while the parties dispute whether the negligent driver was insured.
Can you file an uninsured motorist claim after a motorcycle hit and run?
Yes, uninsured motorist coverage can apply in certain motorcycle hit-and-run cases where the at-fault vehicle cannot be identified, subject to the terms of the policy and applicable New York law. Hit-and-run claims often have special notice and proof requirements (prompt reporting, for instance, and proof that an unidentified vehicle was involved). The coverage may require physical contact, which makes the exact circumstances of the accident very important. A motorcyclist being struck by an unidentified car that then flees presents a different coverage issue than a motorcyclist who crashes after swerving to avoid a vehicle that never made contact. The relevant endorsement and the law will need to be reviewed to determine whether coverage applies. Police reports, security camera footage, witness statements, vehicle damage and photos may all be used to establish the collision. If the at-fault driver is never found, the rider’s own insurance will become a vital source of compensation.
What if a hit-and-run driver forces you off the road without making contact?
A motorcycle accident caused by an unidentified vehicle that causes the rider to be thrown from the bike without any physical contact can create a real problem in terms of uninsured motorist coverage. NY’s statutory uninsured motorist framework and the policy language in force will, in some cases, require physical contact for an unidentified hit-and-run claim. So a rider involved in an accident caused by an unidentified vehicle may end up in a coverage dispute even if they believe the other driver caused the accident. The analysis shouldn’t stop at the mere fact that there was no contact. Surveillance, witness statements, physical evidence, or accident reconstruction may show that there was, in fact, contact with the motorcycle, the rider, or some other object. The rider may also have a claim against a named negligent driver or against some other responsible party. An attorney should properly investigate the matter before concluding there is no uninsured motorist coverage.
Can you sue the uninsured driver personally?
Yes, an injured motorcyclist can bring a personal injury action against a negligent driver even if the driver has no liability insurance. The lack of insurance doesn’t mean the driver isn’t liable for the injuries caused by their negligent conduct. The problem is that you can get a judgment and you can’t necessarily collect on it. A driver with very limited income, very few assets, or a lot of debt may well be unable to satisfy a large judgment. That’s why an attorney would assess the merits of the negligence claim and the prospects of recovery based on the actual sources of recovery. Uninsured motorist coverage may well be the only viable route to recovery in certain circumstances (depending on the policy and the circumstances). Other defendants may also be available (the vehicle owner, the employer, another driver, etc.). The decision to go after an uninsured driver must be based on the evidence, the defenses that might be available, the availability of insurance coverage, and the prospects of collection.
Can you sue the owner of an uninsured vehicle that hits your motorcycle?
A motorcyclist injured by an uninsured vehicle may have a claim against the owner under New York law, which imposes liability on the owner for the negligent operation of a covered vehicle (subject to the law’s requirements and recognized exceptions). This is relevant when the driver who caused the accident did not own the vehicle. For example, the driver may have borrowed the vehicle from a family member, a friend, or a business partner. The owner may be liable under the law even if they were not present at the scene of the collision. The owner must establish ownership, permission, statutory coverage, and other defenses. Certain federal laws may also impact claims against vehicle rental and leasing companies. An attorney would need to obtain the registration records, review the relationship between the driver and the owner, and determine whether any other insurance applies.
What if an uninsured driver was working when they hit your motorcycle?
If an uninsured driver is involved in a motorcycle accident while carrying out duties in the course of their employment, the driver’s employer may be liable under the principles of respondeat superior or another relevant legal theory. A classic example is an uninsured delivery driver, commercial vehicle operator, or employee who has an accident while on the job. The fact that the driver is uninsured doesn’t necessarily mean the employer lacks commercial insurance or some other form of financial responsibility. The employer will be liable in those circumstances depending on the nature of the employment, the nature of the work being carried out and the circumstances of the accident. An independent contractor situation may raise further issues, and a company is not automatically liable just because the driver was using an app or carrying out a delivery. An attorney would need to review the employment history, vehicle ownership, dispatch records, commercial insurance policies, and what the driver was doing at the time of the accident.
Does uninsured motorist coverage pay medical bills after a motorcycle accident?
Uninsured motorist coverage can provide compensation for accident-related medical expenses as part of a covered bodily injury claim, but it’s not the same as medical payments or No-Fault. A motorcyclist generally must prove the uninsured driver was at fault and that the claimed injuries resulted from the accident. The UM insurer will investigate the accident, review the medical records, dispute the extent of the injuries, and assess the claim before paying anything; as such, uninsured motorist coverage should not be assumed to pay ER bills or rehab bills as and when they arise. The injured rider may have to use their own health insurance, Medicare, Medicaid, MedPay (if they have it), or another legal means of payment while the claim is being processed. The eventual recovery may also be subject to policy limits, reimbursement rights, and other applicable rules. It’s important to understand this distinction, as it could leave a rider with a significant financial burden after a serious crash.
Can you recover lost wages through uninsured motorist coverage?
Yes, an injured motorcyclist can pursue legally recoverable lost earnings through applicable uninsured and underinsured motorist coverage when the loss of income results from injuries sustained in an accident caused by a covered negligent driver. Motorcyclists generally don’t get the standard New York No-Fault wage replacement benefits, so lost income can be a real problem. A UM or SUM claim could cover past lost wages, diminished earning capacity, and other covered damages (subject to the policy and proof requirements). Documentation typically includes employer wage statements, tax returns, pay stubs, medical disability notes, and any notes relating to work restrictions. Self-employed riders will need additional business records to establish their income and lost opportunities. The insurer can always challenge whether the injuries actually prevented the rider from working and whether the claimed lost income is properly documented. An attorney should look at both the immediate loss of income and any impact on the rider’s ability to earn in the future.
Can you recover pain and suffering from your own motorcycle insurance company?
Yes, applicable uninsured or underinsured motorist coverage can pay an injured motorcyclist for pain and suffering, which is legally recoverable when an uninsured or underinsured driver is negligent. This depends on the policy’s terms and limits. Unlike No-Fault benefits, which are generally limited to specific economic losses, UM/SUM claims can cover a range of bodily injury damages the insured is legally entitled to recover. Such damages may include physical pain, permanent limitations, disfigurement, and loss of enjoyment of life (where supported by the evidence). Motorcyclists and passengers generally fall outside New York’s Article 51 serious injury threshold, but they still must prove the injuries, their causation, and the damages. The insurer may contest the severity of the injuries or contend that the injuries were attributable in some way to a pre-existing condition. Medical records, diagnostic studies, the treating physician’s opinion, and evidence of daily limitations may all be relevant to the claim’s value.
Do you have to prove the other driver was negligent to get your UM/SUM benefits?
Yes. Uninsured and underinsured motorist coverage will generally require the injured motorcyclist to prove a legal entitlement to damages from the uninsured or underinsured driver. That usually involves establishing that the other driver was negligent, that the negligence caused the accident, and that the rider suffered compensable injuries. The other driver’s uninsured status alone does not establish liability. For example, if an uninsured auto driver makes an unsafe left turn across a motorcyclist’s path, evidence of the driver’s failure to yield may be sufficient to support a UM claim. On the other hand, if the motorcyclist is at fault for the collision and the other driver was not negligent, UM coverage may not provide any compensation. The insurer may also raise comparative fault defenses when the facts support it. Surveillance video, witness statements, traffic signal information, vehicle damage, and accident reconstruction can all help establish liability.
Can your insurance company blame you for the motorcycle accident?
Yes. An uninsured or underinsured motorist insurer can dispute the insured rider’s claim by saying the rider caused or contributed to the collision. The rider may have purchased the insurance, but the insurer can assess liability and damages in the same way a liability insurer would when defending the allegedly negligent driver. The insurer may contend that the rider was speeding, tailgating, or otherwise engaging in an unsafe maneuver. Those allegations will have to be assessed in the light of the actual evidence and the applicable New York comparative fault rules. A traffic violation does not, of itself, establish that the rider was 100% at fault, and the insurer’s initial assessment is not necessarily the end of the matter. The attorney will need to review the accident facts, preserve the video, obtain witness statements, and assess the degree to which the alleged rider conduct caused the collision. A successful challenge to an excessive allocation of fault can have a massive impact on the amount payable under the policy.
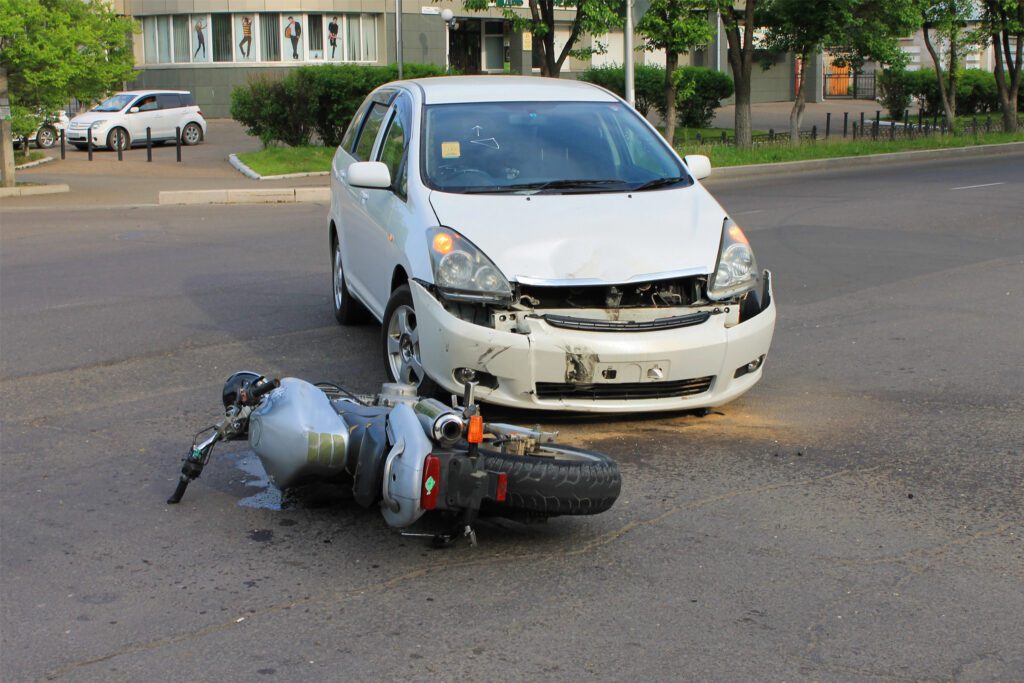
Does New York’s comparative negligence law apply to motorcycle UM/SUM claims?
Comparative negligence affects the amount of damages you can recover under your uninsured/underinsured motorist coverage, as the insurer will generally reduce the amount of damages you’re entitled to recover from the at-fault driver by your percentage of fault. Outside of the scope of Insurance Law Article 51, New York’s normal comparative fault rules will generally reduce the amount of damages recoverable by the injured person by their proportion of fault. So if the rider is found to be 20% at fault in an accident, their otherwise recoverable damages would be reduced by 20%. Of course, the applicable statute, policy language, and the posture of the proceeding must be looked at carefully. The 2026 amendments to CPLR § 1411 introduced different rules for certain actions under Article 51, so properly classifying the vehicle and the statute at issue matters. Motorcyclists generally fall outside the No-Fault coverage of Article 51, so an attorney should not assume the same rules that apply to covered automobile occupants will apply. The insurer must have evidence to support its allegations of fault.
What is the deadline to report an uninsured motorist motorcycle accident?
Uninsured motorist claims may be subject to prompt notice provisions as set out in the policy and as required by New York law. Certain hit-and-run claims have specific requirements for a police report and insurer notification. The exact requirements will vary depending on the type of accident, the coverage and the applicable endorsement. An injured rider should therefore notify the relevant insurer promptly and seek legal advice rather than assume the normal three-year personal injury statute of limitations applies in every instance. Underinsured motorist claims can also be subject to requirements for notice of the negligent driver’s insurance limits, notice of a proposed settlement, and the insurer’s right to defend. Failure to comply with the applicable requirements may give rise to a coverage dispute. The consequences of late notice will, of course, depend on the law and the circumstances. An attorney should review the policy and determine the requirements rather than relying on a general time limit.
Can you settle with the at-fault driver before making a SUM claim?
A motorcyclist must be very careful when considering settling with an underinsured driver when a potential SUM claim may arise. NY SUM endorsements generally include provisions for notice of a proposed settlement and the insurer’s right to protect its subrogation rights. If the negligent driver’s liability limits and release are accepted without complying with the SUM provisions, a dispute can arise over the rider’s entitlement to the supplementary benefits. In certain situations, the SUM insurer must be notified of a proposed settlement and will have the opportunity to respond under the relevant endorsement. The policy and New York insurance regulations will govern the procedure and timing. An attorney can coordinate the settlement of the liability with the potential SUM claim, obtain the required documentation, and determine whether the proposed release will protect the rider’s rights. A settlement that looks good on the surface may become a financial disaster if it inadvertently strips the rider of additional coverage.
What is SUM arbitration in New York?
SUM arbitration is a process by which entitlement to supplementary uninsured/underinsured motorist benefits under an applicable New York policy may be determined. If the injured rider and the insurer cannot agree on liability, damages, or another arbitrable issue, the claim may go before an arbitrator rather than in an ordinary personal injury trial against the insurer. The applicable endorsement and procedural rules govern how the arbitration is initiated and conducted. Evidence may include police reports, witness testimony, medical records, expert opinions, and documentation of economic loss. The insurer may contest the at-fault driver’s liability, the causation of the rider’s injuries by the accident, or the amount of damages. Some disputes as to the existence or extent of coverage may require a judicial determination rather than resolution through the damages arbitration process. An attorney should of course determine the appropriate forum and preserve all applicable procedural rights.
Can you sue your own insurance company for denying UM/SUM coverage?
An injured motorcyclist may have legal recourse if the insurer improperly denies UIM (uninsured/underinsured motorist) benefits. The right course of action depends on the nature of the dispute. Some disputes will be over liability or the amount of damages and may be settled through arbitration pursuant to the policy. Other disputes will be over coverage issues (e.g., whether the injured party is an insured, whether the at-fault vehicle is an “insured” as defined in the policy, whether an exclusion applies, etc.). Those types of disputes may require litigation or some other form of legal action. The mere fact that an insurer has denied a claim does not, by itself, establish bad faith or create a separate entitlement to punitive damages. The attorney will have to review the policy, the denial letter, the claim history, the applicable regulations, and the legal basis for the insurer’s position. Act promptly, as contractual and statutory time limits may apply to available remedies.
Can you recover UM/SUM benefits if you were riding someone else’s motorcycle?
An injured person on someone else’s motorcycle may be eligible for uninsured/underinsured motorist benefits under an applicable policy (though eligibility will depend on the policy language, the definition of insured, and the facts of the situation). The policy of the motorcycle owner may provide coverage to qualifying operators and/or passengers. The injured rider may also have other policies to consider, although priority and exclusions can be very complex. For example, the rider may own another motorcycle or car, live with a family member who has applicable coverage, or be insured under a particular endorsement. That doesn’t necessarily mean that they can combine policies or that they will be covered under a separate automobile policy. New York insurance law and the policies in question will determine eligibility, coverage priority, and available limits. An attorney should have full copies of all potentially relevant policies before they can say definitively that the rider is not covered.
Can a motorcycle passenger recover under uninsured motorist coverage?
Yes. A motorcycle passenger injured by an uninsured or underinsured driver may have access to applicable UM/SUM coverage, depending on the policy and the accident circumstances. Passengers generally do not control the motorcycle, and they may have claims against a negligent automobile driver, the motorcycle operator, or other responsible parties. If the negligent driver is uninsured, the motorcycle’s applicable uninsured motorist coverage may provide an important source of compensation. Additional insurance policies may also require review, depending on the passenger’s insured status and the governing coverage provisions. However, coverage availability is not determined solely by the fact that the person was a passenger. You must evaluate policy definitions, exclusions, coverage priority, and liability. An attorney should investigate the conduct of all involved drivers and identify every potentially applicable insurance policy.
Can You Stack Multiple Uninsured Motorist Policies in New York?
The ability to combine uninsured or underinsured motorist coverage from multiple policies is limited by New York law and the applicable policy provisions. Riders should not assume that owning several insured vehicles or having access to family members’ policies automatically allows them to add the coverage limits. New York SUM endorsements contain provisions addressing coverage limits, priority, and anti-stacking rules. The analysis may differ depending on whether the policies cover separate vehicles, whether the injured person qualifies as an insured, and whether different insurers are involved. For example, a motorcyclist who owns a motorcycle and an automobile may have two policies, but that does not necessarily mean both policies provide collectible benefits for the same accident. An attorney should review the declarations, endorsements, insured-person definitions, and applicable regulatory requirements before calculating available coverage.
What if the Uninsured Driver Was Operating a Stolen Vehicle?
A motorcycle accident involving a stolen automobile may create complicated liability and uninsured motorist coverage issues. The person driving the stolen vehicle may be legally responsible for negligent or reckless operation. Still, the vehicle owner’s liability insurance may dispute coverage because the vehicle was being operated without permission. Vehicle and Traffic Law § 388 generally addresses owner responsibility for permissive operation, so the lack of permission may be important. However, the coverage analysis depends on the facts, insurance contracts, and applicable legal rules. If the stolen vehicle lacks applicable liability insurance for the collision, uninsured motorist coverage may become relevant, subject to the policy and statutory requirements. Police reports, theft records, ownership information, and insurance correspondence may be important evidence. An attorney should investigate the vehicle’s status and available coverage rather than assuming that every accident involving a stolen vehicle automatically qualifies for UM benefits.
What if the Uninsured Driver Flees New York or Cannot Be Located?
An injured motorcyclist may still have a potential uninsured motorist claim when the responsible driver leaves New York or cannot be located. Still, the driver’s absence does not automatically establish that the vehicle was uninsured. If the driver’s identity and insurance information are known, the applicable liability policy may remain available even if the driver disappears. If the vehicle was uninsured, the rider’s UM coverage may provide a separate avenue for compensation. The legal procedures for establishing the driver’s responsibility and pursuing insurance benefits depend on the circumstances. A personal injury lawsuit against an identified driver may also be possible, although service and collection issues can become more difficult when the defendant cannot be located. An attorney should investigate vehicle registration, ownership, insurance records, police reports, and other available information while preserving applicable insurance notice and filing rights.
What if You Do Not Have Uninsured Motorist Coverage on Your Motorcycle?
If an injured rider believes there is no uninsured motorist coverage, the first step is to review the complete motorcycle insurance policy and determine whether statutory coverage exists. New York generally requires basic uninsured motorist bodily injury protection in qualifying motorcycle liability policies, but disputes may arise if the motorcycle was uninsured, the policy lapsed, or the injured person does not qualify as an insured. Additional policies may also require examination. If no applicable insurance benefits are available, the rider may still have a negligence claim against the responsible driver or other legally liable parties. However, collecting compensation from an uninsured individual can be difficult. The attorney should investigate vehicle ownership, employment relationships, commercial coverage, and other potential sources of recovery. The rider’s health insurance and other benefits may also matter for immediate medical treatment, even though those benefits do not replace a liability recovery.
Does MVAIC Cover Motorcycle Accident Victims in New York?
The Motor Vehicle Accident Indemnification Corporation, commonly called MVAIC, provides a statutory compensation mechanism for certain eligible victims of uninsured or unidentified motor vehicle accidents, but motorcycle cases require careful analysis. Because motorcycle operators and passengers are generally excluded from ordinary New York No-Fault benefits, a rider should not assume that MVAIC will pay motorcycle accident medical bills simply because the negligent driver was uninsured. Eligibility for any available MVAIC remedy depends on the claimant’s status, the accident circumstances, applicable insurance coverage, and the governing statutory requirements. Different rules may apply to pedestrians or other injured persons who are not occupying a motorcycle. MVAIC also has specific notice and procedural requirements. An attorney should determine whether the injured person qualifies for any available remedy before recommending an application, rather than treating MVAIC as a substitute for motorcycle uninsured motorist insurance.
How Long Do You Have to File a Lawsuit Against an Uninsured Driver in New York?
Most negligence-based motorcycle accident personal injury lawsuits in New York must be commenced within three years under CPLR § 214(5), but shorter deadlines and special requirements may apply depending on the defendant and circumstances. A claim against New York City or another governmental entity may require a Notice of Claim within 90 days and compliance with a shortened lawsuit deadline. Wrongful death claims generally have a two-year limitations period measured from the date of death, subject to applicable law. Insurance claims involve additional requirements that may arise well before the ordinary personal injury statute of limitations. UM/SUM notice, settlement-consent procedures, arbitration demands, and contractual limitation provisions require separate review. An injured rider should not assume that having three years to sue the negligent driver means there are three years to notify the rider’s own insurer. Prompt legal review helps preserve all potential sources of recovery.
What Evidence Is Needed for an Uninsured or Underinsured Motorcycle Accident Claim?
A strong uninsured or underinsured motorist claim requires evidence establishing how the collision occurred, the negligent driver’s responsibility, the available insurance coverage, and the rider’s damages. Police reports, witness statements, surveillance recordings, photographs, and vehicle damage may help establish liability. Insurance declarations, policy endorsements, coverage denial letters, and documentation of the negligent driver’s policy limits are important when determining whether UM or SUM benefits apply. Medical records, diagnostic imaging, treatment histories, and expert opinions may establish the nature and severity of the injuries. Wage records, tax returns, and employment documentation can support claims for lost earnings and diminished earning capacity. Hit-and-run cases may require additional evidence of physical contact and compliance with applicable reporting requirements. Because coverage disputes can hinge on specific policy language and deadlines, an attorney should preserve both accident evidence and insurance documentation from the start of the claim.
Should You Accept the At-Fault Driver’s Policy Limits Without Speaking to a Lawyer?
An injured motorcyclist should be cautious about accepting a policy-limits settlement without first investigating other available coverage and the potential consequences for a SUM claim. A negligent driver may offer the full $25,000 bodily injury limit, but the rider’s medical expenses and long-term losses may be far greater. Accepting that payment may require signing a release that affects claims against the driver or other parties. It may also trigger consent and notice requirements under an applicable SUM endorsement. An attorney should determine whether commercial insurance, employer coverage, excess policies, additional defendants, or supplementary benefits may provide further compensation. The proposed settlement should also be evaluated in light of medical liens, reimbursement obligations, and future treatment needs. A policy-limits offer is not necessarily the maximum amount legally recoverable from all responsible parties and insurance sources.
How Can a New York City Motorcycle Accident Lawyer Help With a UM/SUM Claim?
A New York City motorcycle accident lawyer can investigate the collision, determine whether the negligent driver was uninsured or underinsured, identify applicable policies, and pursue compensation through the appropriate insurance procedures. The attorney may obtain liability insurance information, review motorcycle policy endorsements, preserve notice rights, and coordinate settlements with potential SUM claims. When an insurer disputes liability or damages, counsel can gather surveillance footage, witness testimony, medical evidence, and expert analysis to support the rider’s position. The attorney can also evaluate whether arbitration, litigation, or another proceeding fits the particular dispute. In serious injury cases, the legal team should consider future medical expenses, lost earning capacity, permanent disability, and pain and suffering rather than focusing solely on immediate bills. Early representation can be especially valuable when the negligent driver lacks insurance, the available limits are inadequate, or the rider faces pressure to accept a quick settlement.
Why Choose Greenstein & Pittari, LLP?
Motorcycle accident victims face unique insurance challenges under New York law. Unlike many automobile accident victims, injured motorcycle riders generally cannot rely on ordinary No-Fault benefits to pay their medical bills and replace lost income. When the negligent driver is uninsured or carries only minimum liability coverage, the financial consequences can become even more serious. At Greenstein & Pittari, LLP, our attorneys understand how uninsured and underinsured motorist claims work and how insurance companies may attempt to limit the compensation available to injured riders. We investigate every potentially applicable insurance policy and pursue legally available sources of recovery.
Our firm brings decades of experience representing injured New Yorkers in serious personal injury cases. We examine the circumstances of motorcycle collisions, identify negligent drivers and other responsible parties, preserve evidence, and evaluate available liability, commercial, and supplementary insurance coverage. When an insurance company disputes a claim, we prepare the evidence necessary to challenge unsupported defenses and pursue appropriate legal remedies. Our attorneys understand that serious motorcycle injuries may involve surgery, extended rehabilitation, permanent disability, substantial lost earnings, and significant pain and suffering. We work to document those losses and prepare cases for litigation and trial when necessary.
We also believe that injured clients deserve responsive communication, personal attention, and clear explanations of their legal options. Greenstein & Pittari, LLP serves motorcycle accident victims throughout Manhattan, Brooklyn, Queens, the Bronx, Staten Island, Long Island, and Westchester County. Our English and Spanish-speaking staff help make legal representation accessible, and clients can communicate with our team by phone, text, email, or through our secure client portal. We are committed to keeping clients informed and treating them with the respect they deserve throughout the legal process.
If an uninsured driver injured you, an underinsured driver, or a hit-and-run motorist, do not assume that the absence of adequate liability insurance means you have no legal options. Our attorneys can investigate the accident, examine your insurance coverage, identify potentially responsible parties, and explain the compensation that may be available.
Call Greenstein & Pittari, LLP at 1-800-VICTIM2 (1-800-842-8462) for a free consultation, available 24/7.
Our Fee Guarantee: No Fee Unless Successful.
Don’t Be a Victim Twice.